What Does Health Insurance Cover in Dubai?
Healthcare in Dubai offers access to modern hospitals, specialist doctors and advanced medical facilities, but quality healthcare can also come with significant costs. This is where health insurance becomes an important financial safeguard for residents, families and professionals.
Dubai’s health insurance system is regulated by the Dubai Health Authority (DHA), and the emirate has a mandatory health insurance framework. The Essential Benefits Plan (EBP) establishes a minimum level of coverage, while broader private policies can provide additional benefits depending on the plan selected.
But what exactly does a policy pay for? Understanding what does health insurance cover in Dubai can help you choose appropriate protection instead of selecting a policy based only on its premium.
Hospitalisation and Inpatient Treatment
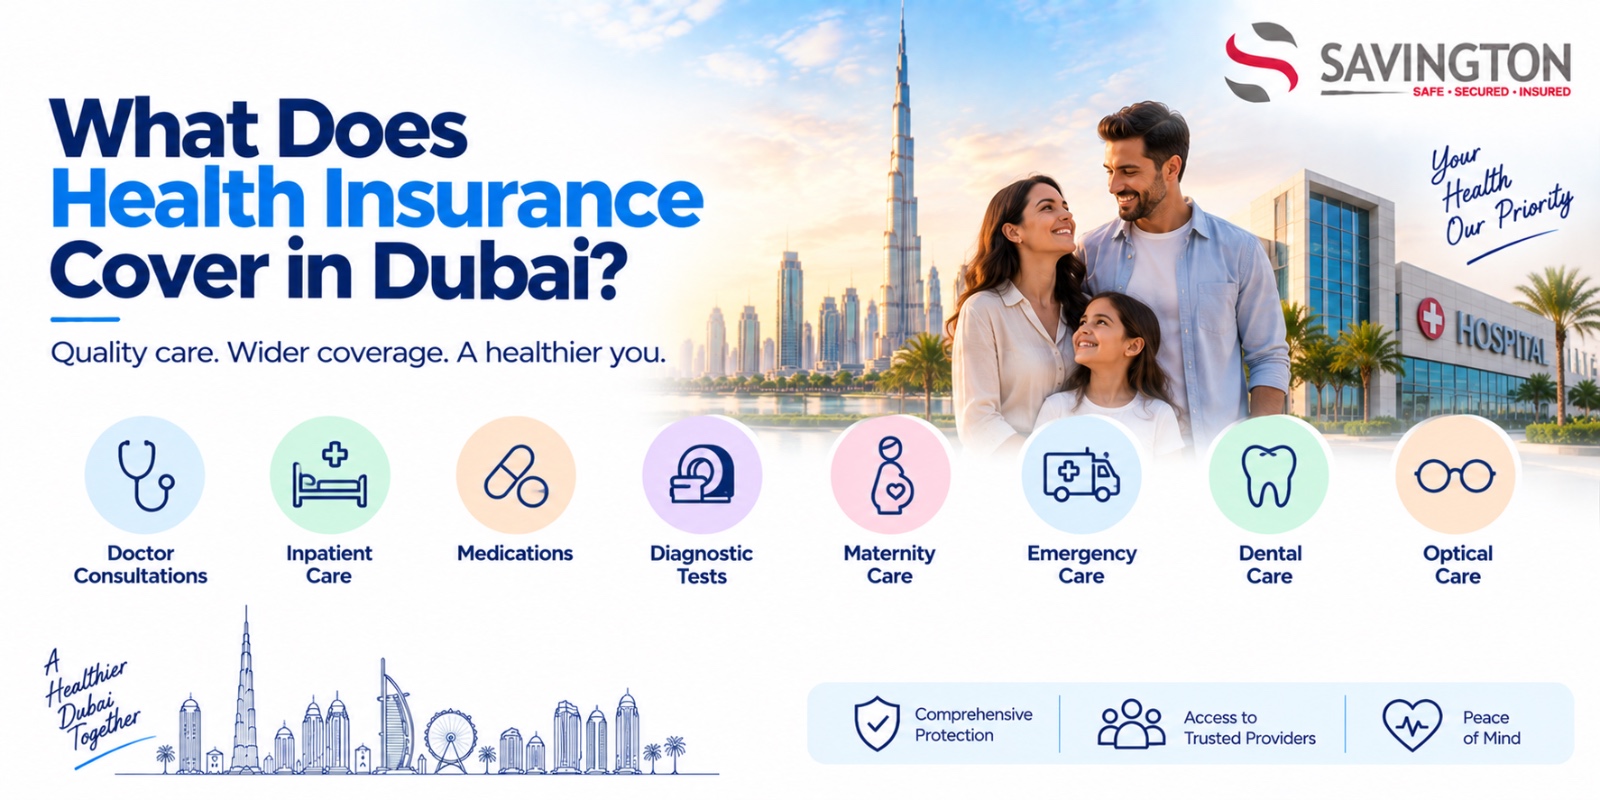
One of the most important components of health insurance in Dubai is inpatient treatment. This generally relates to medical care that requires you to be admitted to a hospital.
Depending on the policy, coverage may include hospital room charges, doctor fees, surgery, nursing services, diagnostic investigations and other medically necessary treatment associated with an admission. Emergency hospital treatment can also form part of the coverage.
However, the exact benefits, limits and provider network can vary significantly between policies. A basic plan may provide essential protection, while a more comprehensive policy may offer access to a wider selection of hospitals and higher coverage limits.
Before choosing best health insurance in Dubai, check the annual benefit limit, room category, hospital network, deductible and co-payment requirements.
This is particularly important for families or individuals who already have preferred hospitals or specialist doctors.
Outpatient and Everyday Healthcare
Health insurance is not only about major hospital stays. Outpatient care can be equally important because it covers many of the medical services people use during the year without being admitted to a hospital.
Depending on the plan, this may include general practitioner consultations, specialist appointments, diagnostic tests, laboratory investigations and prescribed medicines.
DHA’s guidance explains that the Essential Benefits Plan includes inpatient and outpatient treatment as part of its minimum healthcare coverage framework.
For someone comparing health insurance benefits, the outpatient component deserves particular attention. A policy with affordable premiums but high consultation co-payments or restricted outpatient benefits may become expensive if you regularly visit doctors.
Checking the list of covered providers is also important because insurers generally operate through defined healthcare networks.
Emergency, Maternity and Essential Care
Unexpected medical situations are one of the main reasons people purchase comprehensive health insurance in Dubai. Emergency treatment can help protect policyholders from having to manage substantial medical expenses during sudden illness or injury.
Maternity coverage can also be available depending on the policy and applicable terms. However, maternity benefits often come with specific conditions, waiting periods, limits or exclusions, so they should never be assumed to be automatically included.
Medication coverage is another useful benefit. Depending on the policy, prescribed medicines may be covered subject to the insurer’s terms, approved formularies, co-payments and limits.
The DHA’s Dubai Health Investment Guide states that the Essential Benefits Plan includes emergency care, maternity services and medication among its essential healthcare services.
When looking for affordable health insurance in Dubai, therefore, compare the actual benefits rather than simply choosing the lowest premium.
What May Not Be Fully Covered
Understanding exclusions is just as important as knowing what is covered. Not every healthcare expense is automatically paid by an insurance policy.
Depending on the plan, certain treatments, elective procedures, cosmetic treatments, specific medications, dental or optical services may have separate conditions or may not be included in the basic coverage.
Pre-existing medical conditions can also be subject to specific underwriting rules, waiting periods, exclusions or coverage conditions depending on the policy and applicable regulations.
This is why reading the policy schedule, exclusions and benefit table is essential before purchasing health insurance in Dubai.
Co-payments and deductibles should also be checked carefully. DHA explains that coinsurance represents a percentage of medical costs paid by the policyholder, while a deductible is a fixed amount paid by the policyholder before or as part of the covered expense, depending on the policy structure.
A policy may therefore appear inexpensive initially but involve higher out-of-pocket expenses when you actually use it.
Choosing the Right Level of Coverage
No single policy is automatically the best health insurance in Dubai for everyone. A young professional, a family with children, a senior citizen and someone managing an existing medical condition can have completely different healthcare requirements.
Start by considering how frequently you visit doctors, which hospitals you prefer, whether you need maternity benefits, your prescription requirements and whether you need dental or optical coverage.
Then compare annual limits, hospital networks, outpatient benefits, emergency coverage, co-payments, deductibles and exclusions.
For residents arranging their own insurance, the goal should be to find a balance between affordability and meaningful protection. A more comprehensive plan can cost more, but it may provide wider healthcare access and greater financial protection.
At Savington, the focus should be on helping customers understand these differences before selecting a policy. Rather than asking only what a plan costs, look at what it actually provides when you need medical care.
Final Thoughts
Understanding what does health insurance cover in Dubai is the first step towards making a smarter insurance decision. From hospitalisation and outpatient consultations to emergency treatment, maternity services and medication, coverage can vary considerably between policies.
Dubai’s mandatory insurance framework establishes essential protection, but individuals can choose plans with benefits beyond the minimum requirements.
Before buying, compare the coverage, network, limits, exclusions and out-of-pocket costs. The right comprehensive health insurance in Dubai should not simply be affordable—it should provide meaningful protection when you and your family actually need healthcare.
MUST READ: Health Insurance Brokers in Dubai: Why DHA-Approved Isn’t Just a Checkbox
Get a Quote Today!
Let us help you protect your business and your employees with our comprehensive Workmen’s Compensation Insurance solutions.
Contact us at +971 4 3962333 (Savington Insurance Brokers Dubai) or visit https://savington.ae/ to learn more about our insurance offerings.
 ×